VAT Refund Estonia: Rules, Eligibility and How to Apply
If your company pays more deductible VAT on business purchases than it owes on sales, you may be entitled to a refund. The VAT refund Estonia process allows eligible businesses to recover excess input VAT under specific conditions. However, the rules depend on your company’s VAT registration, business activities and where it is established.
For entrepreneurs operating through Estonia’s e-Residency programme, understanding these rules is an important part of managing business expenses and tax compliance.
How VAT Refund Estonia Works for Businesses
In Estonia, VAT-registered businesses generally calculate two types of VAT:
- Output VAT: VAT charged on taxable sales.
- Input VAT: VAT paid or payable on eligible business purchases.
When deductible input VAT exceeds output VAT during a reporting period, the difference may be refunded.
Estonia’s standard VAT rate is 24%, effective from 1 July 2025.
For example, if a company has €1,000 in output VAT and €1,500 in deductible input VAT, it may have a €500 refund claim.
The actual refund depends on the company’s eligibility, deductible expenses and tax obligations.
The procedure is regulated by § 34 of the Estonian Value-Added Tax Act.
Who Can Reclaim VAT in Estonia?
A company must meet specific requirements before recovering VAT.
Most importantly, ordinary VAT registration and VAT registration with limited liability are not the same.
An ordinarily VAT-registered taxable person may deduct input VAT on purchases used for taxable business activities, subject to legal restrictions.
However, a person registered only as a податкова особа з обмеженою відповідальністю (piiratud maksukohustuslane) cannot deduct input VAT.
This distinction is particularly relevant for businesses registered because they receive services from foreign suppliers. Having a VAT identification number does not automatically establish deduction rights.
Under § 25(1) of the Value-Added Tax Act, taxable persons with limited liability have no right to deduct input VAT.
For ordinary VAT-registered companies, eligibility also depends on whether:
- Purchases support taxable business activities.
- Invoices and supporting documents meet legal requirements.
- Expenses are not subject to specific deduction restrictions.
Companies conducting both taxable and exempt activities may have only partial deduction rights.
How to Apply for a VAT Refund
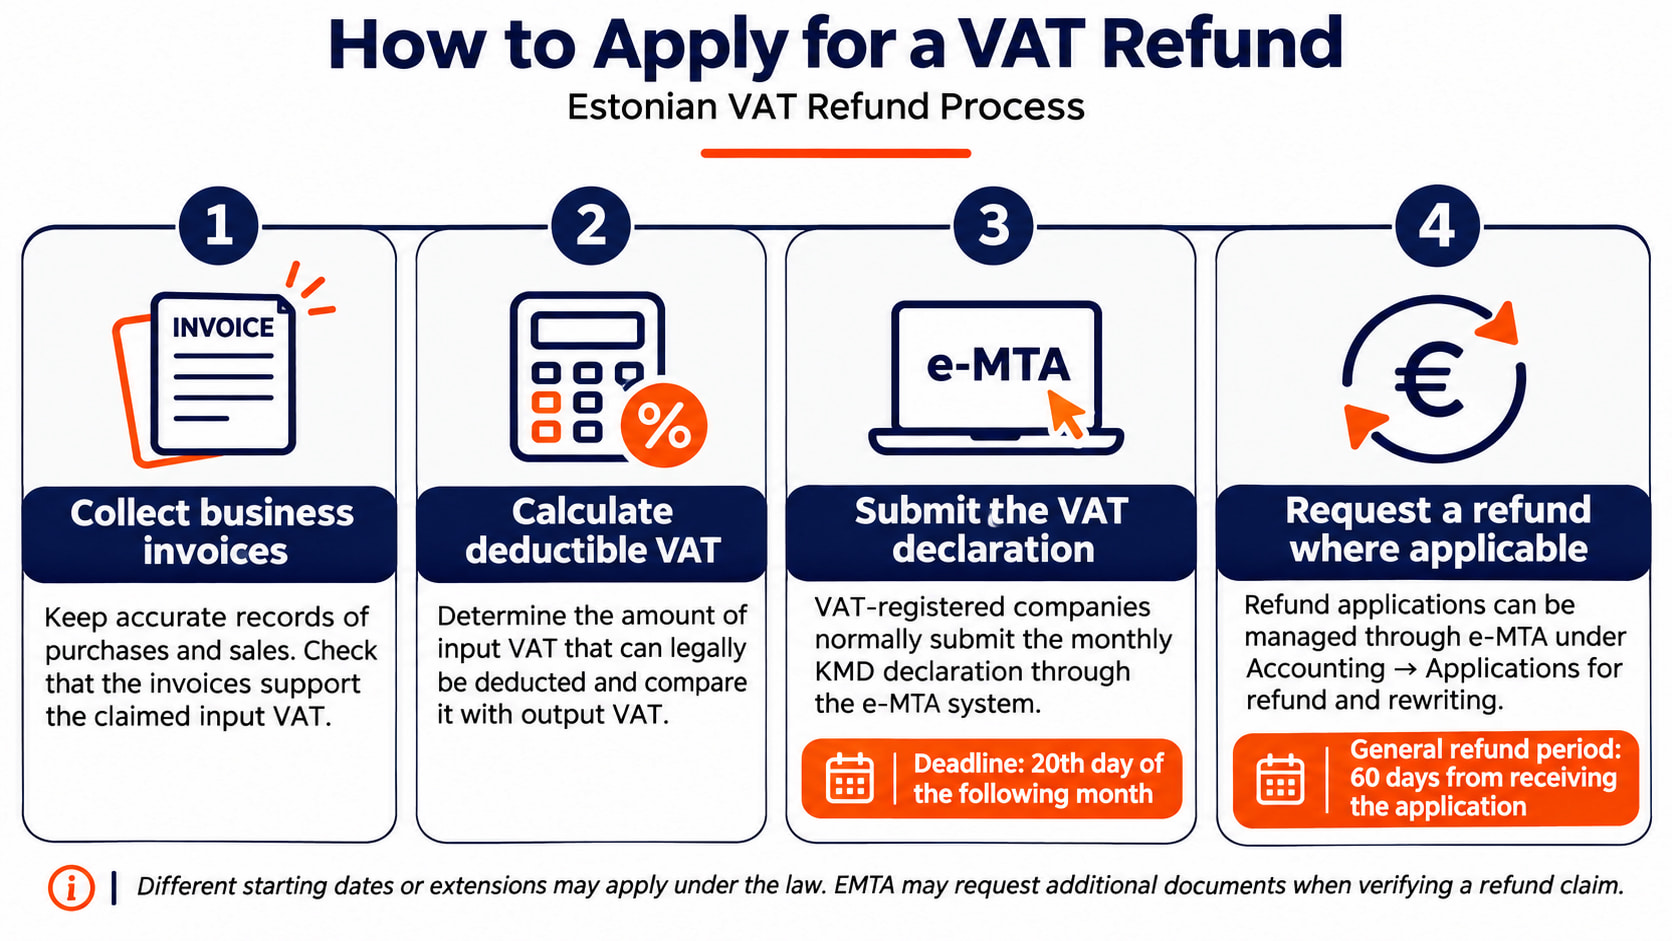
For an Estonian VAT-registered company, the process is connected to regular VAT reporting.
Step 1: Collect business invoices
Keep accurate records of purchases and sales. Check that the invoices support the claimed input VAT.
Step 2: Calculate deductible VAT
Determine the amount of input VAT that can legally be deducted and compare it with output VAT.
Step 3: Submit the VAT declaration
VAT-registered companies normally submit the monthly KMD declaration through the e-MTA system.
The general deadline is the 20th day of the following month.
Step 4: Request a refund where applicable
Refund applications can be managed through e-MTA under Accounting → Applications for refund and rewriting.
According to the Естонський податковий та митний департамент, the general refund period is 60 days from receiving the application. Different starting dates or extensions may apply under the law.
EMTA may request additional documents when verifying a refund claim.
VAT Refund Estonia for EU Businesses
Businesses established in another EU Member State may also reclaim eligible Estonian VAT without using ordinary Estonian VAT returns, provided the conditions for the foreign refund procedure are satisfied.
Applications are generally submitted electronically through the tax authority in the company’s home Member State.
The deadline is 30 September of the calendar year following the refund period.
Minimum refund amounts
Under Directive 2008/9/EC, Articles 16 and 17, the following thresholds apply:
| Refund period | Minimum amount |
|---|---|
| At least three months but less than a calendar year, excluding the year-end remainder | €400 |
| Full calendar year | €50 |
| Remainder of a calendar year, even if shorter than three months | €50 |
A €400 minimum does not apply to every refund period shorter than a year.
Deduction rights in the home country
Another important condition is that the applicant must carry out activities giving the right to deduct VAT in its Member State of establishment.
If the company conducts both activities that give deduction rights and activities that do not, the applicable partial deduction proportion limits the refund.
Estonian VAT deduction restrictions also apply to the relevant expenses.
These requirements are established in Directive 2008/9/EC, Article 6 and § 35 of the Estonian Value-Added Tax Act.
Безкоштовна консультація
Спростіть роботу вашої естонської компанії дистанційно
Silva Hunt підтримує цифрові підписи, електронні послуги, бухгалтерські інструменти, введення банківських операцій, вимоги до контактних осіб та повсякденні робочі процеси, які роблять віддалене управління компанією більш плавним.
VAT Refunds for Non-EU Businesses
Companies established outside the European Union may also qualify for refunds of Estonian VAT, but different rules apply.
The ordinary non-EU procedure generally follows the principle of reciprocity. Estonia refunds VAT to qualifying businesses from countries that provide corresponding refund rights to Estonian taxable persons.
Under the ordinary procedure:
- The minimum refund amount is €320 per calendar year.
- The application deadline is 30 September of the year following the relevant calendar year.
- VAT on the acquisition of immovable property is excluded from this refund procedure.
The ordinary application also requires invoices and evidence of the applicant’s VAT liability in its country of establishment.
Exception for businesses using OSS
An important exception applies to qualifying non-EU businesses using the relevant One Stop Shop (OSS) special scheme.
For input VAT connected with supplies covered by that scheme, the ordinary reciprocity and home-country VAT-liability conditions do not apply.
The implementing regulation also provides an exception to the ordinary requirement for a home-country VAT-status certificate in these qualifying cases.
The exception does not remove other applicable VAT deduction and refund restrictions.
These rules are explained in § 35 of the Value-Added Tax Act, Minister of Finance Regulation No. 66 і EMTA’s guidance for non-EU taxable persons.
Common Restrictions on VAT Refunds
Not every business purchase qualifies for a full VAT deduction or refund.
Estonian legislation limits input VAT deduction in several situations.
Серед прикладів можна назвати:
- Passenger cars: Input VAT deductions are generally limited to 50% for qualifying passenger cars and related expenses, unless a statutory exception applies.
- Guest reception and certain employee expenses: Input VAT on guest reception, meals and employee accommodation is generally restricted, subject to statutory exceptions.
- Exempt business activities: Expenses connected with VAT-exempt supplies may not qualify for deduction.
- Mixed business and private use: Deduction may be limited where expenses are not used entirely for taxable business purposes.
For non-EU applicants using the ordinary foreign refund procedure, the exclusion relating to immovable-property acquisitions must also be considered.
The applicable restrictions are detailed in EMTA’s input VAT deduction guidance.
VAT Refund Estonia for E-Resident Companies
For companies established through Estonia’s e-Residency programme, VAT refund rules work in the same way as for other Estonian companies.
E-Residency alone does not create VAT registration or deduction rights.
Before requesting a refund, we should review the company’s VAT registration type, the nature of its business activities and the expenses involved.
For businesses operating internationally, it is also important to distinguish between:
- Estonian input VAT, which may be deductible through ordinary Estonian VAT returns.
- VAT paid in another EU country, which may qualify for a refund through the EU refund system.
- VAT on expenses connected with exempt or partly deductible activities, which may be restricted.
An Estonian company seeking a refund from another EU country must also consider the deduction rights applicable in Estonia and the refund restrictions of the other Member State.
More details are available in EMTA’s guidance on VAT paid in another Member State.
За адресою Сільва Хант, we help entrepreneurs manage VAT accounting, business expenses and tax reporting in Estonia. Our team can review your company’s VAT situation and help determine the appropriate reporting and refund procedure.
Need assistance with VAT accounting or a refund in Estonia? Contact Silva Hunt to discuss your company’s situation.
Автор: Дарія Хіміченко, менеджер з маркетингу компанії Silva Hunt.